30/9/26
What I Spent This Week as a Digital Marketing Manager Making $65K
Ever wondered how others really manage their money?

Ever wondered how others really manage their money?
In the A Week in My Wallet series, we share it all, because talking about money shouldn't be off-limits.
Every week, an anonymous member shares a week of their spending: no names, no filters, just honest stories about life's everyday financial choices.
Ready to join the conversation and help make money talk less taboo? Share your own story via our form here.
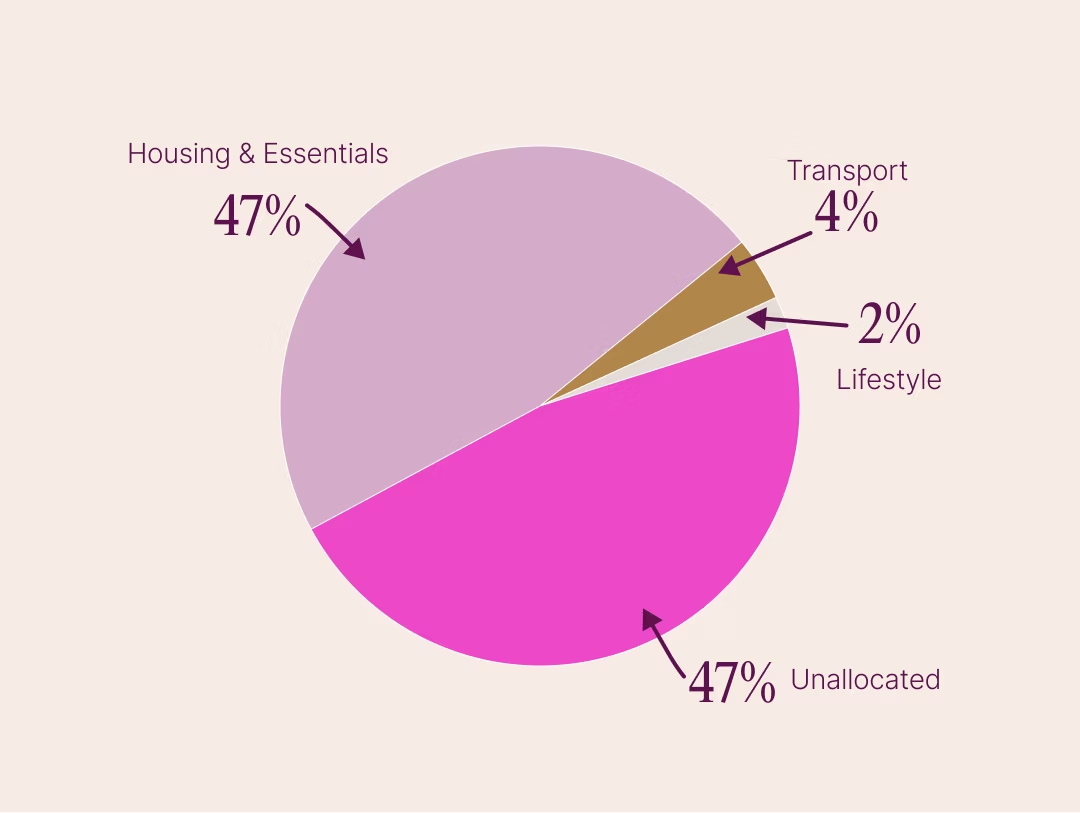
Monthly Take-Home Pay (after tax): £3,000 ($3,960)
Do you share expenses with someone?: Yes, my husband
Household Income (if shared): £7,300 ($9,636)
What is your overall monthly budget?
- Rent + bills + groceries (goes into a shared bank account) - £1,400 ($1,848)
- Other bills (gym, phone) - £65 ($86)
- Transport - £115 ($152)
Amount left each month after essentials (to spend, save or invest): £1,500 ($1,980)
Dependents (if any): None
My Relationship with Money
Growing up, did your parents or guardians educate you around money?
No, not really. My parents taught me the value of money, that it comes with hard work and that it shouldn't be wasted on meaningless things. But at the same time, they never really talked to me about investing or saving in a more practical and actionable way.
What was your first job and why did you get it?
My first job was as a paid marketing intern in a tech start-up. I was looking to get practical experience while still at Uni.
Did you worry about money growing up?
I didn't. I grew up in quite a well off family. My parents came from no money at all and worked really hard to get to where they did, establishing and growing their own business, and providing all the best for their children as the result. So while I didn't have to worry about money growing up, I was very aware it doesn't 'grow on trees'.
At what age did you become financially responsible for yourself and do you have a financial safety net?
I became fully financially responsible for myself only at 25, which on reflection, seems rather late? I have an emergency fund that is probably my main financial net, but I also have a support of my husband and could ask family for help too, if an extreme situation called for it.
Do you worry about money now?
Yes. While overall it feels like I'm on a somewhat average for UK salary, with the cost of living in London, it does mean I don't have that much left after the rent and bills are paid. I'm not living a particularly lavish lifestyle, but I also don't deny myself too much in terms of small pleasures like going to an exhibition, or a meal out with friends, making an occasional small unexpected purchase -this is something I can just about afford now, but I don't think I'd be able too if I was living on my own and had to cover rent by myself.
Same goes to saving and investing, I can do a bit of it but now, but as much as I would want to, unless I change my lifestyle and live more frugally. Current job market also worries me, having to rely on only one source of income. This is something I am looking to and working on changing.
What is your biggest money regret?
Not starting to invest sooner and keeping savings in a rather low yield savings account for a really long time.
What financial goals are you working towards?
Saving for a deposit for a house purchase and finding a way to increase my income without changing my job (by adding additional income streams).
Who is your financial role model (if any), and why?
Not sure I have one...
My mum is my role model when it comes to starting a business and raising a family, but when it comes to finances, there are some big mistakes that she's acknowledged she made. The lack of educating us kids on finances is also something I would change.
Reflections on My Spending Habits:
As long as I stay at home - I don't spend much money so maybe I should do that more often! On a more serious note, I think I'm fairly reasonable with me spending, but if I am out and about, I tend to get impulse purchases, even if fairly small ones.
What I Spent in a Week
Day 1: Monday – £11.05 ($15)
- £7.20 ($10) — Travel by Tube to central London for a talk after work.
- £3.85 ($5) — Meal deal at Tesco, bought for the next day. I worked from home and had leftovers for lunch so no expenses during the day otherwise.
Day 2: Tuesday – £0 ($0)
- £0 ($0) — Worked from home and had meal deal bought the day before.
Day 3: Wednesday – £14 ($18)
- £14 ($18) — Paid tailor for fixing two pairs of trousers. Worked from home again and had no other expenses.
Day 4: Thursday – £8.80 ($12)
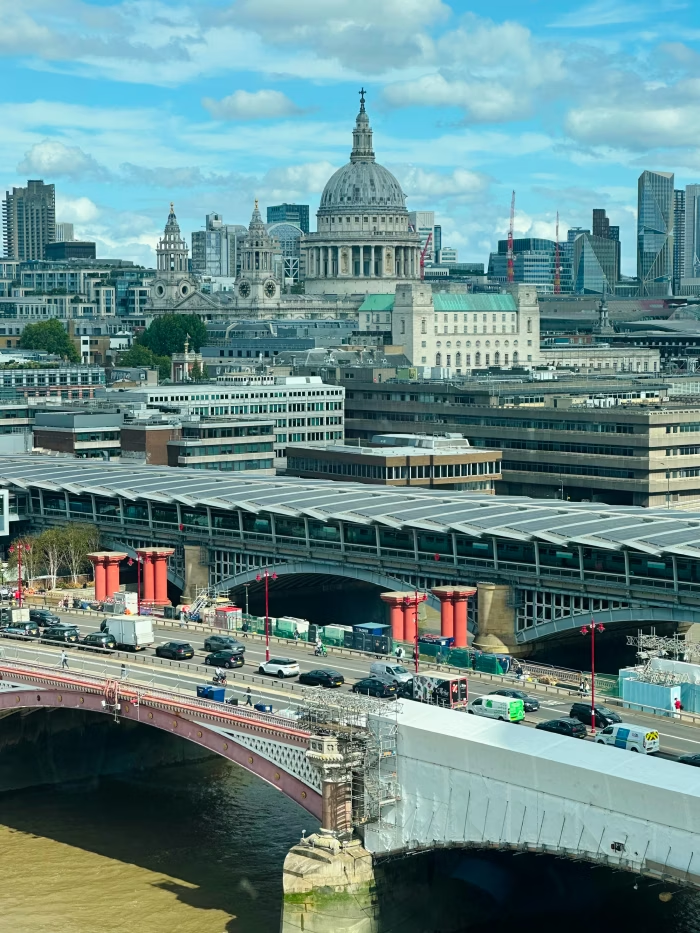
- £7.20 ($10) — Travelled to central London for a work conference.
- £1.60 ($2) — Got a soft drink.
Day 5: Friday – £58.40 ($77)
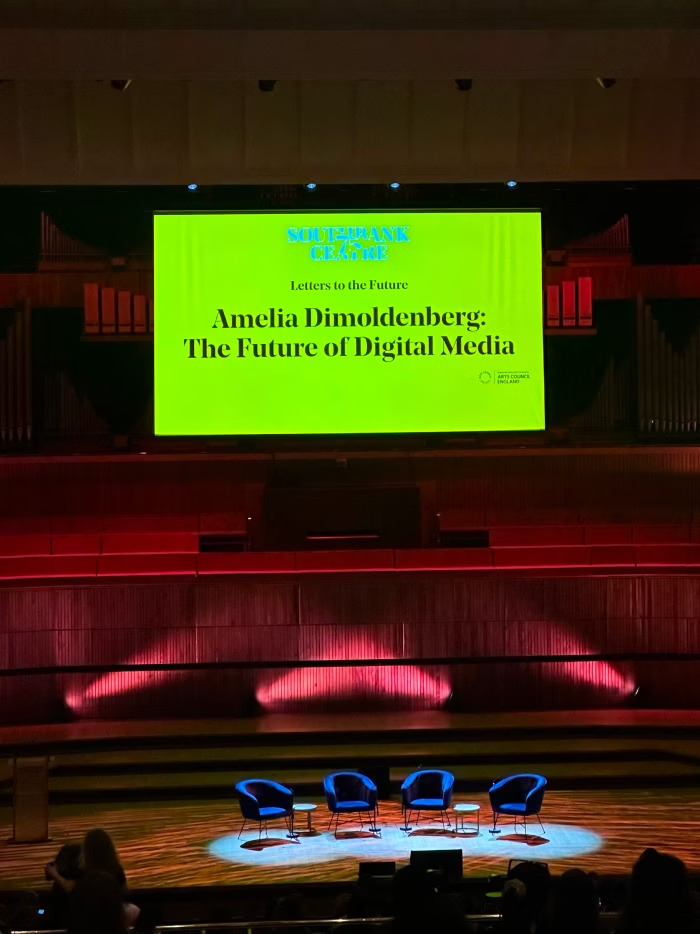
- £7.20 ($10) — Travel to central London for a talk by Amelia Dimoldenberg (£20 ($26) for a ticket paid in the previous month).
- £51.20 ($68) — Ordered lenses online (~2 months supply).
Day 6: Saturday – £62.20 ($82)
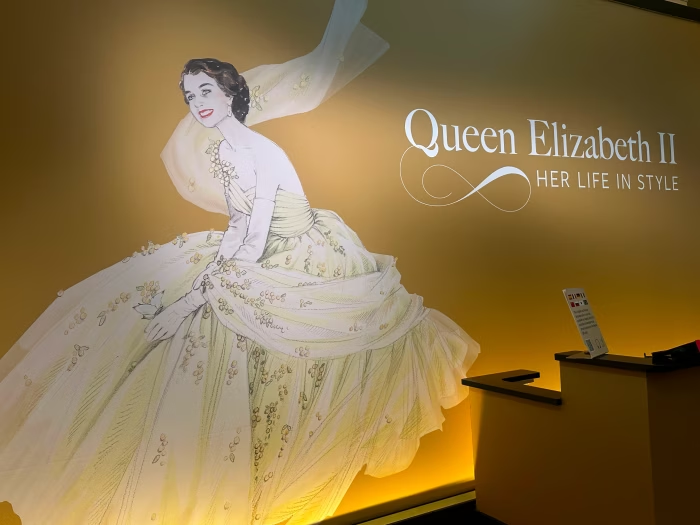
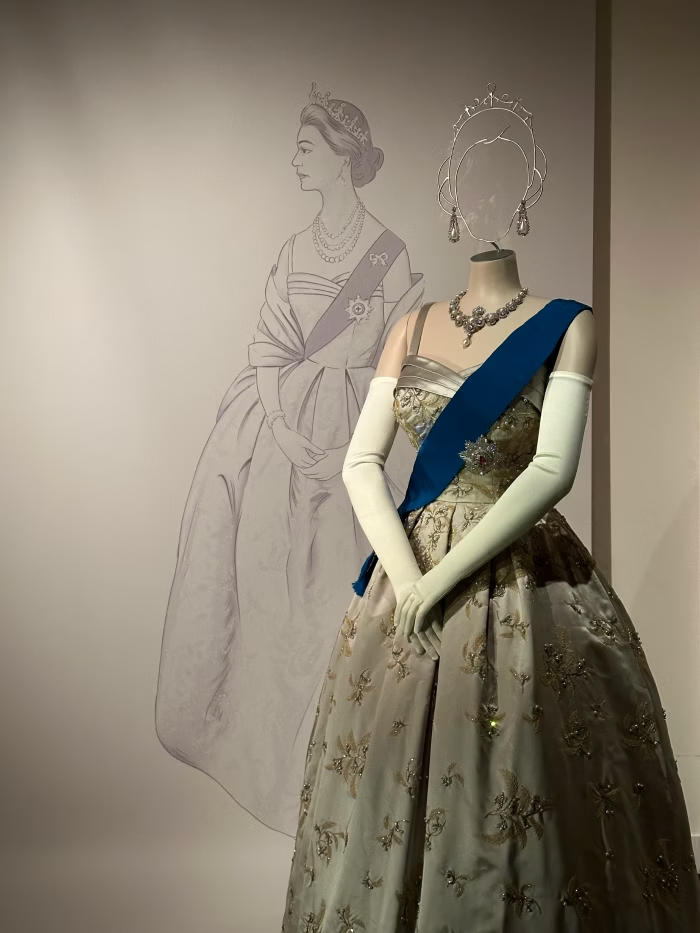
- £17 ($22) — Souvenirs bought at the Queen Elizabeth's fashion exhibition.
- £7.20 ($10) — Travel to central London.
- £35 ($46) — Brunch with a friend.
- £3 ($4) — To print exhibition tickets (to convert to a yearly pass).
Day 7: Sunday – £24 ($32)
- £24 ($32) — Bought some groceries at Tesco.
Total Weekly Spend: £178.45 ($236)